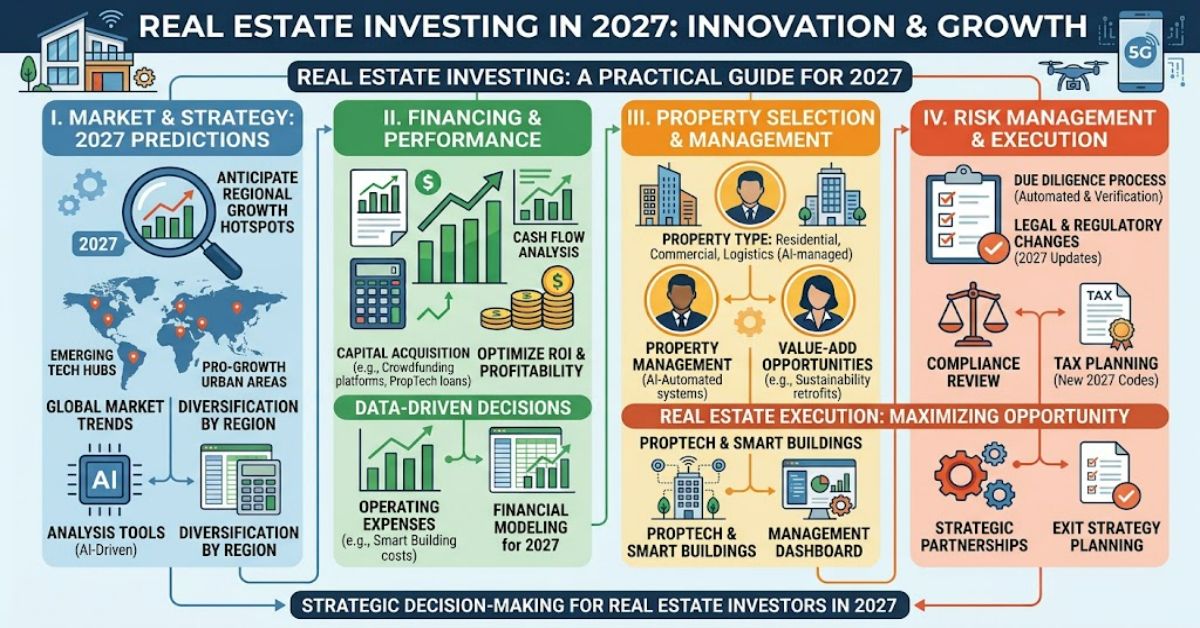
Real estate investing involves buying property to generate rental income, short-term profits or long-term capital appreciation. For many investors, the appeal is straightforward: property is a tangible asset that can produce recurring income while potentially increasing in value over time.
But the economics are more complicated than a property’s advertised price or monthly rent suggests. A successful investment has to absorb mortgage interest, stamp duty, maintenance, insurance, management costs, void periods, taxation and unexpected repairs. Leverage can magnify returns when prices and rents perform well, but it can also magnify losses when financing costs rise or income falls.
The UK market illustrates this tension. In September 2026, the Office for National Statistics reported that average UK house prices had risen 1.4% year on year to £273,000 in July 2026, while average private rents had increased 3.8% to £1,400 a month in August.
That does not automatically make property attractive. An investor must compare the expected net return with the cost of capital and the risks attached to the particular property. Location, tenant demand, property condition and local supply can matter more than broad national price movements.
How Real Estate Investing Works
There are several ways to participate in the property market.
| Strategy | Main return source | Key risk |
| Buy-to-let | Rental income and appreciation | Interest, vacancy and regulation |
| Property renovation | Value created through improvement | Construction costs and resale risk |
| Development | Development profit | Planning, finance and construction |
| Commercial property | Rent and capital growth | Tenant and economic risk |
| Property funds/REITs | Income and market appreciation | Market-price volatility |
Buy-to-let is the most familiar model for individual investors. The basic calculation is rental yield:
Gross rental yield = Annual rent ÷ Property purchase price × 100
For example, a £200,000 property producing £12,000 in annual rent has a gross yield of 6%. However, that figure excludes mortgage interest, repairs, insurance, management fees, taxes, service charges and periods without a tenant.
A more useful measure is net yield because it reflects the costs required to operate the property.
The Costs Investors Often Underestimate
The purchase price is only the beginning of the capital requirement.
In England and Northern Ireland, SDLT applies to residential property purchases above the relevant thresholds. From 1 April 2025, additional residential properties generally attract a 5-percentage-point surcharge on the standard residential rates.
For example, a £300,000 additional property can generate £20,000 of SDLT under the higher-rate structure before legal fees, mortgage costs or renovation expenditure are considered.
Financing is another major variable. The Bank of England maintained Bank Rate at 3.75% in September 2026, while warning that energy-price pressures could affect inflation. Mortgage rates therefore remain a central consideration when modelling leveraged property.
Individual residential landlords also face restrictions on the tax treatment of finance costs. HMRC states that, from April 2020, residential finance-cost relief for individual landlords is restricted to a basic-rate tax reduction.
These factors make a high gross yield less meaningful if the property’s financing and operating costs consume most of the income.
Regulation Has Become Part of the Investment Case
Property investors increasingly need to treat regulation as an operating issue rather than an administrative afterthought.
The Renters’ Rights Act 2025 introduced major changes to private renting in England from 1 May 2026. These include the abolition of Section 21 no-fault evictions and the conversion of assured shorthold tenancies into assured periodic tenancies.
For landlords, this changes the risk calculation around tenant management, possession procedures and compliance. It also reinforces the importance of maintaining properties properly and understanding legal obligations before purchasing.
The practical implication is significant: a property can have an attractive yield on paper but become less attractive if its management burden, compliance requirements or potential refurbishment costs are high.
What the Current Market Tells Investors
Recent data suggest a market that is growing, but not uniformly.
| Indicator | Latest reported figure | Investment implication |
| UK average house price | £273,000 | Capital growth is positive but modest |
| Annual house-price growth | 1.4% | Appreciation should not be the sole investment thesis |
| UK average private rent | £1,400/month | Rental demand remains important |
| Annual rent growth | 3.8% | Rental income is growing faster than house prices |
| Bank Rate | 3.75% | Financing remains a material cost |
Sources: Office for National Statistics; Bank of England.
One useful insight is the gap between rental and house-price growth. With rents rising faster than average house prices in the latest ONS data, income-focused investors may find rental economics more important than relying on rapid capital appreciation.
A second insight is that national averages can conceal local differences. ONS data show meaningful variation in rent inflation between UK regions. That means investors should examine local rents, employment, transport links, housing supply and tenant demographics rather than using a national yield as a proxy for a specific neighbourhood.
A third insight is that regulation and financing can alter investment returns without any change in the property’s market value. A flat worth £250,000 can remain worth £250,000 while its owner’s net cash flow changes substantially because of mortgage rates, tax, maintenance or tenancy rules.
The Future of Real Estate Investing in 2027
The property investment environment in 2027 is likely to reward financial discipline more than speculative optimism.
Interest rates will remain an important variable. The Bank of England’s published 2027 schedule confirms that monetary-policy decisions will continue throughout the year, making borrowing costs an ongoing consideration for leveraged investors.
Rental regulation will also remain significant. Investors in England will need to operate under the post-May-2026 tenancy framework, while compliance, tenant communication and possession procedures become increasingly important parts of property management.
The likely competitive advantage will therefore belong to investors who can buy selectively, control operating costs, maintain adequate reserves and withstand periods of weaker capital growth.
Key Insights
- Yield is only a starting point: Net cash flow provides a better picture than headline rental yield.
- Leverage cuts both ways: Borrowing can improve equity returns but increases exposure to interest-rate and vacancy risk.
- Taxes affect acquisition economics: SDLT can materially change the amount of capital required at purchase.
- Regulation has financial consequences: Tenancy reforms can affect management processes, risk and operating costs.
- Local analysis beats national averages: Property performance depends heavily on local supply, demand and tenant economics.
- Cash reserves matter: Unexpected repairs, void periods and refinancing costs can undermine otherwise attractive investments.
- Exit strategy should come first: Investors should understand how they could sell, refinance or restructure the asset before committing capital.
Conclusion
Real estate investing remains a potentially useful way to build income and long-term wealth, but it is not a passive shortcut to financial security. The strongest investment cases are built from realistic numbers rather than optimistic assumptions about rising property prices.
The UK market in 2026 presents a mixed picture. House prices are growing modestly, rents are rising faster, borrowing costs remain meaningful and regulatory requirements have become more demanding.
For investors, that makes disciplined underwriting essential. Purchase price, rental yield, mortgage costs, taxation, maintenance, vacancy and compliance should all be modelled before a transaction is agreed. A property that works only when everything goes right is not necessarily a good investment.
The central lesson is simple: property should be evaluated as a business asset, not merely as a physical asset. The quality of the cash flow, the resilience of the financing structure and the investor’s ability to manage risk ultimately determine whether the strategy creates sustainable returns.
FAQ
What is real estate investing?
Real estate investing involves purchasing property or gaining property exposure to generate rental income, capital appreciation or profits from development and resale.
Is real estate investing profitable?
It can be, but profitability depends on purchase price, rental income, financing, taxes, maintenance, vacancy rates and eventual selling costs.
What is rental yield?
Rental yield measures annual rental income against the property’s purchase price. Gross yield excludes operating expenses, so investors should also calculate net yield.
Is buy-to-let still worthwhile in the UK?
It can suit investors with sufficient capital, realistic cash-flow assumptions and strong knowledge of local demand. Tax, financing and rental regulation need to be included in the assessment.
What are the biggest risks in property investment?
Major risks include falling prices, higher borrowing costs, vacancy, unexpected repairs, weak tenant demand, regulatory changes and insufficient cash reserves.
How much money is needed to start investing in property?
There is no universal minimum. Required capital depends on the property price, deposit, taxes, financing costs, transaction expenses and reserve needed for unexpected expenditure.
Methodology
This article combines the supplied editorial brief with current UK housing, taxation, monetary-policy and rental-regulation information from the Office for National Statistics, HM Revenue & Customs, GOV.UK and the Bank of England. Current market figures were checked against September 2026 ONS and Bank of England publications. Regulatory claims were checked against government guidance concerning SDLT, residential landlord taxation and the Renters’ Rights Act 2025.
The analysis is limited by the use of national statistics, which cannot predict the performance of an individual property. Rental yields, financing terms, taxes and local market conditions vary considerably. Readers should obtain professional tax, mortgage and legal advice before making a property investment decision.
References
Bank of England. (2026). Monetary Policy Summary and Minutes, September 2026.
HM Revenue & Customs. (2026). Stamp Duty Land Tax: Residential property rates.
HM Revenue & Customs. (2026). Income Tax when you rent out a property: Working out your rental income.
Ministry of Housing, Communities and Local Government. (2026). Renters’ Rights Act: An overview for landlords.
Office for National Statistics. (2026). Private rent and house prices, UK: September 2026.